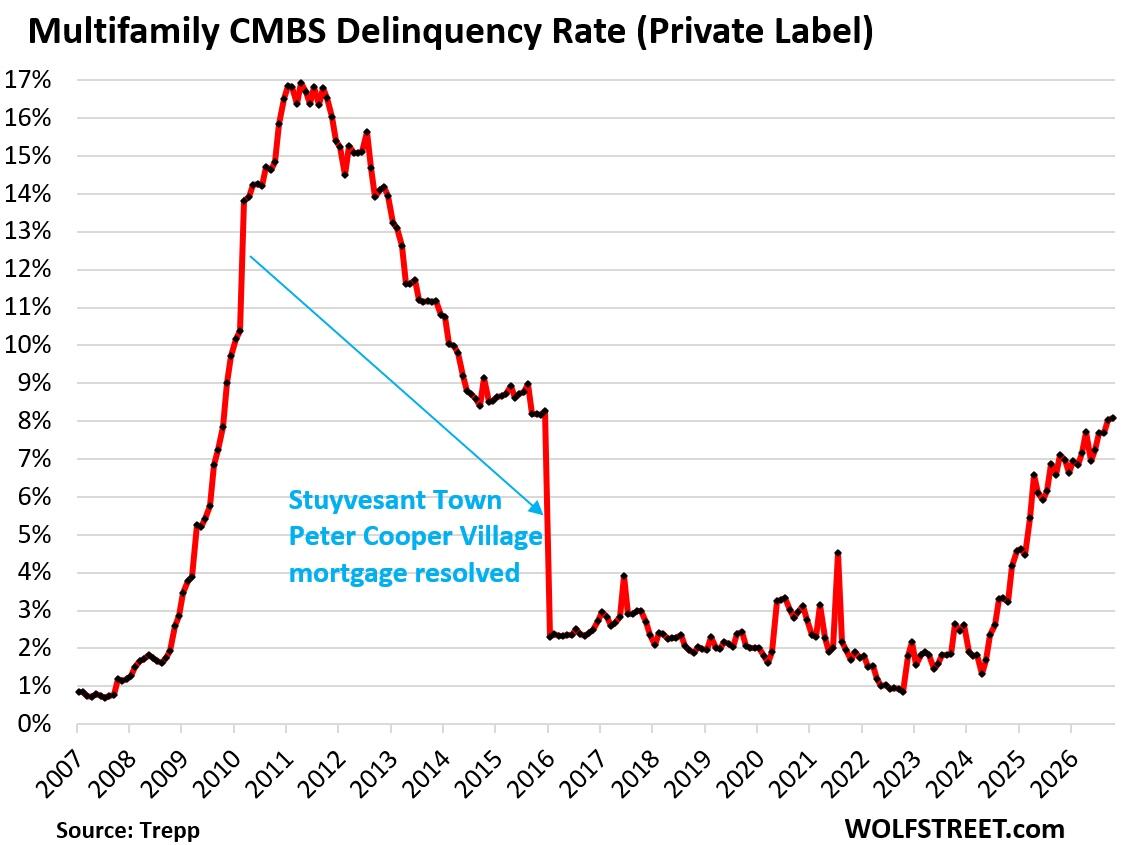
The multifamily commercial real estate (CRE) market is experiencing a significant downturn, with approximately $2.3 trillion in loans outstanding, backed by buildings with rental apartments. The US government, through Fannie Mae and Freddie Mac, holds about $1.2 trillion of this debt, putting taxpayers at risk.
The remaining debt is held by various entities, including banks, insurance companies, and real estate funds, which are now facing defaults due to higher interest rates making it difficult to refinance loans. A recent example of this is the default on a $210 million interest-only mortgage on a waterfront apartment property in Tiburon, California, known as The Cove at Tiburon.
The mortgage, which was issued in 2020, became delinquent when it couldn't be refinanced at current interest rates due to declining rental income. This default has contributed to a rise in the multifamily CMBS delinquency rate to 8.1% in October, the highest since 2016.
Another lender, Bridge Investment Group, has been affected by a defaulted $360 million loan on a high-end apartment tower in downtown Los Angeles, The Beaudry. The loan, which was used to develop the 64-floor tower, cannot be refinanced at today's interest rates without a significant capital infusion, leading the developer, Brookfield, to hand over the keys and walk away from the property.
Bridge Investment Group is now trying to sell the loan and the rights to the property. The situation is expected to continue to deteriorate, with many more defaults likely to occur in the coming months.